How SSS, PhilHealth, Pag-IBIG and withholding tax are taken
See what each government deduction is based on, when payroll takes it, and where it shows on the payslip.
Updated Oct 2, 2026
Before you start
Two places control these deductions. Only the business owner can open Payroll Settings. Owners and managers can change an employee's Deductions card.
In Payroll Settings, the General card has SSS, PhilHealth, Pag-IBIG. It decides which cutoff takes them. A cutoff is the half of the month that one payroll run covers. Click Save after changing it.
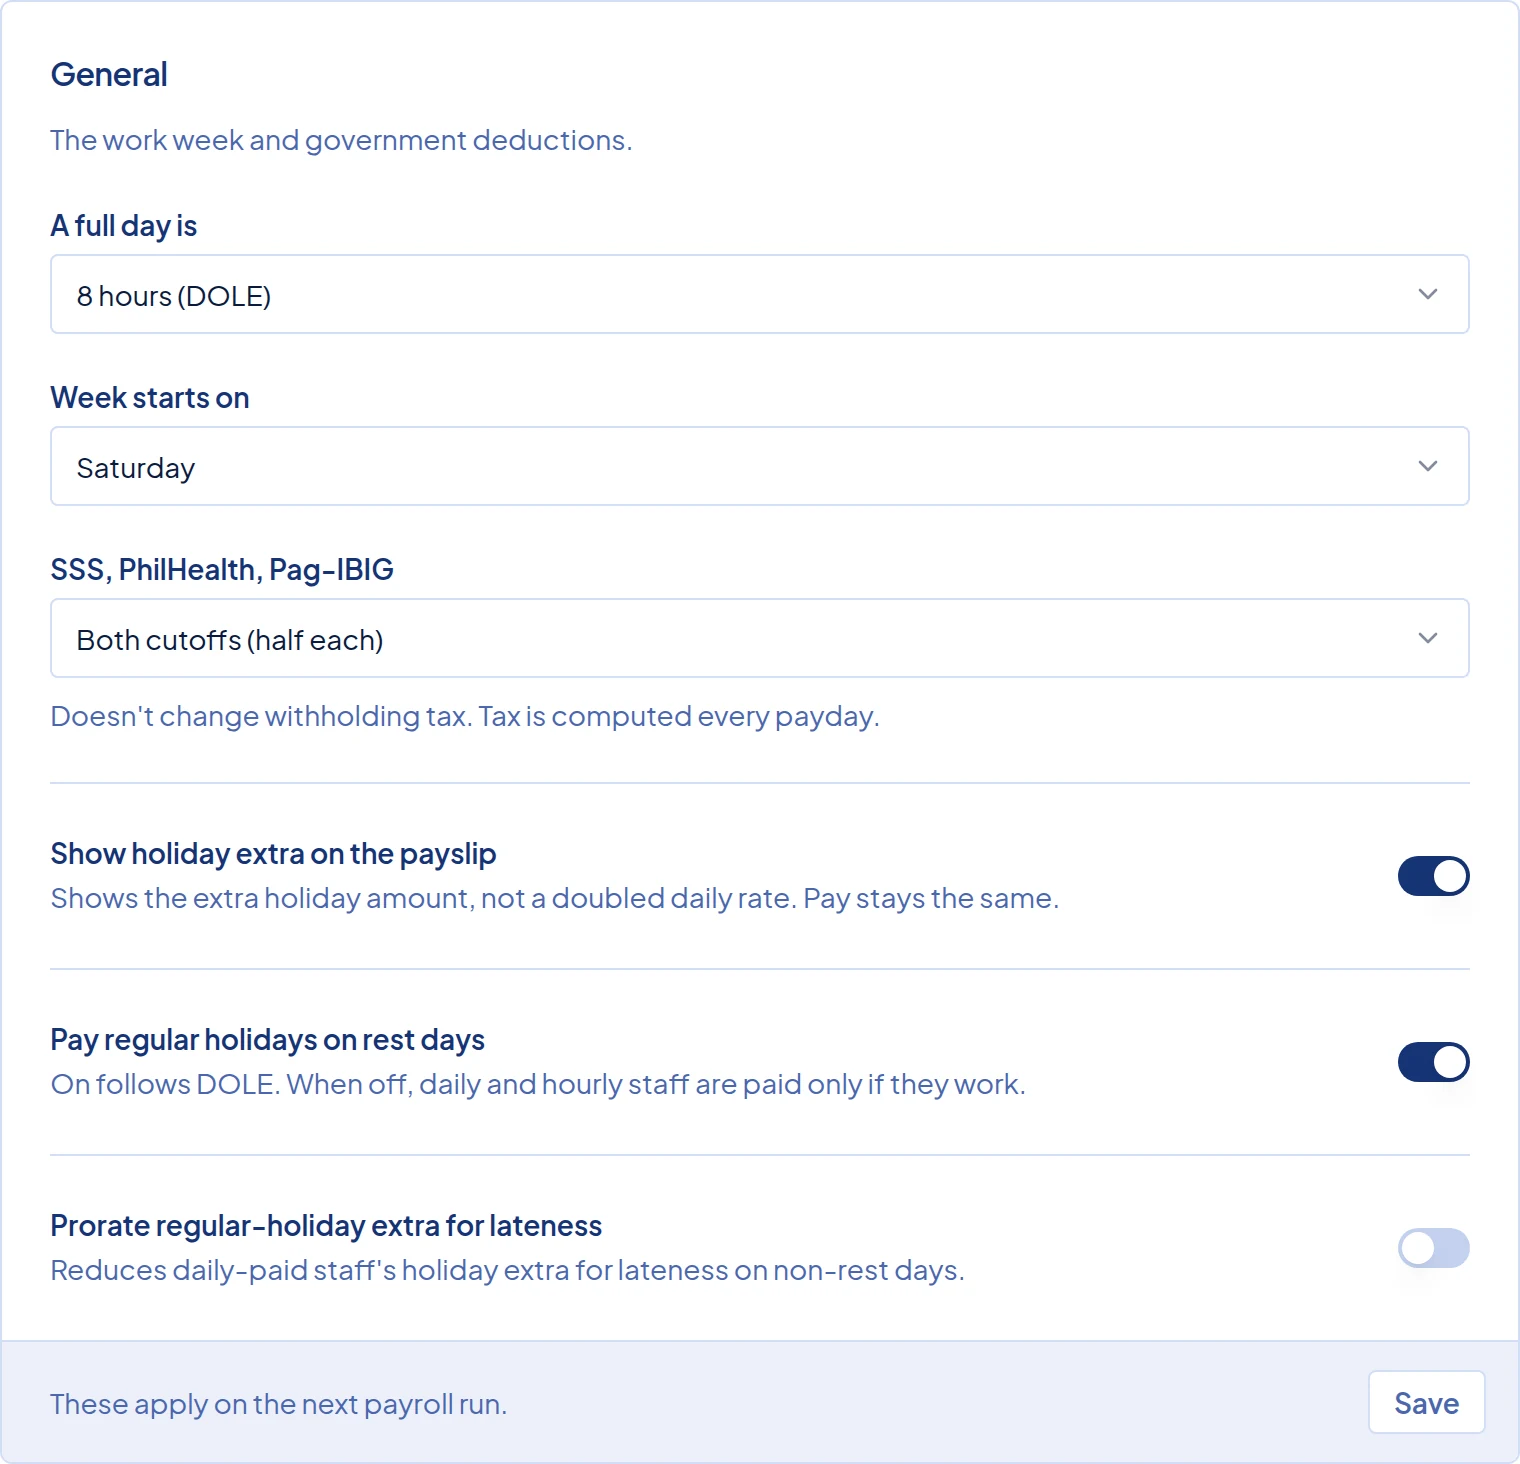
The General card in Payroll Settings. SSS, PhilHealth, Pag-IBIG is set to Both cutoffs (half each). Open an employee in Staff and find the Deductions card on their page. Its Government Contribution Schedule can replace the company setting for this person. Leave it on Use Company Default otherwise. Deduct Government Contributions turns SSS, PhilHealth and Pag-IBIG on or off together. Each one also has its own switch, as does Withholding Tax, and all are on for a new employee. Leave the fixed monthly amount boxes empty so payroll uses the rates below. Click Save Changes at the bottom of the page.
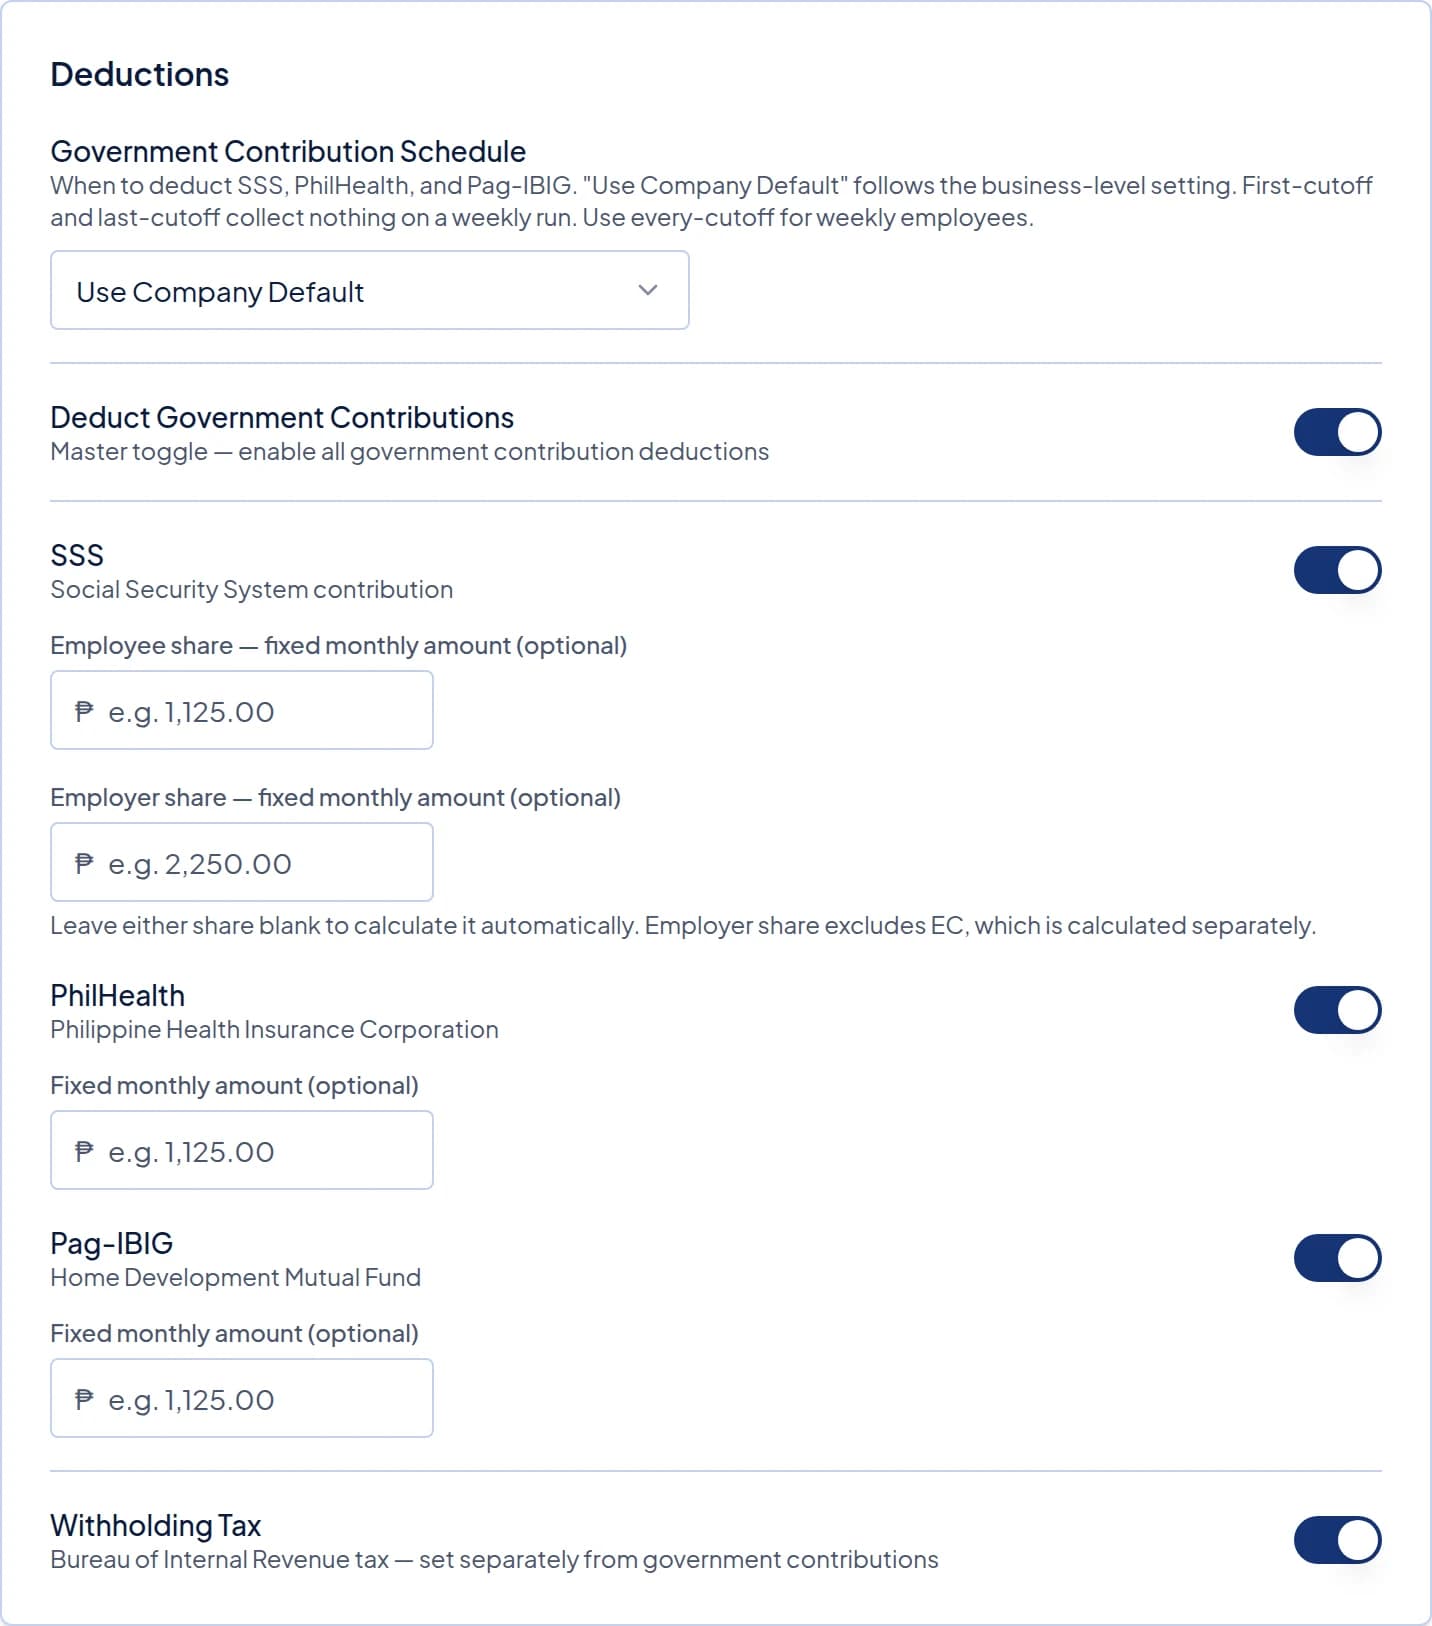
The Deductions card on an employee's page, with the schedule, the master switch, and a switch for each deduction.
What happens next
When you click Run Payroll, payroll works out a whole month, then takes a share of it on each payroll run.
- SSS uses gross pay, including overtime, holiday pay and taxable allowances, after late, undertime, overbreak and absence deductions. It is rounded to the nearest ₱500, from ₱5,000 to ₱35,000. The employee pays 5% and the employer 10%. The employer also pays Employees' Compensation (EC) of ₱10, or ₱30 from ₱14,750 a month.
- PhilHealth is 5% of basic pay, split equally between employee and employer. Basic pay under ₱10,000 counts as ₱10,000, and over ₱100,000 as ₱100,000. Monthly staff use their Monthly Rate.
- Pag-IBIG is 2% each from the employee and the employer, on basic pay up to ₱10,000, so at most ₱200 each. If that pay is ₱1,500 or less, the employee pays 1%.
- Withholding tax uses the BIR table on every payroll run. It taxes the same pay minus that run's employee SSS, PhilHealth and Pag-IBIG. Nothing is taken up to ₱10,417 a cutoff, or ₱4,808 a week.
For Daily, Hourly and Monthly staff, the 1st cutoff doubles its pay to estimate the month. The 2nd cutoff adds both cutoffs and takes what is left. Fixed Semi-Monthly staff are figured on each cutoff's pay times two, including taxable allowances, and that same amount is used for PhilHealth and Pag-IBIG instead of basic pay. Weekly payroll uses the week times four.
The SSS, PhilHealth, Pag-IBIG setting has three choices:
- Both cutoffs (half each) spreads the month over both cutoffs, or takes a quarter each week on weekly payroll.
- 1st cutoff only and Last cutoff only take the whole month on that cutoff, and nothing on weekly payroll.
Tax is taken on every payroll run, whichever you choose.
For example, Ana earns ₱1,000 a day on Both cutoffs (half each). She works 13 days in the 1st cutoff, so her pay is ₱13,000 and her month is estimated at ₱26,000.
- SSS: 5% of ₱26,000 is ₱1,300 for the month, so the 1st cutoff takes ₱650.
- PhilHealth: her half of 5% is 2.5% of ₱26,000, or ₱650 for the month, so the 1st cutoff takes ₱325.
- Pag-IBIG: 2% of the ₱10,000 cap is ₱200 for the month, so the 1st cutoff takes ₱100.
Her taxable pay is ₱13,000 − ₱650 − ₱325 − ₱100 = ₱11,925. Tax is (₱11,925 − ₱10,417) × 15% = ₱226.20.
The payslip lists each one under Deductions: SSS Contribution, PhilHealth Contribution, Pag-IBIG Contribution and Withholding Tax on the dashboard, and SSS, PhilHealth, Pag-IBIG and Withholding Tax in the employee portal. A line is hidden when it is ₱0. The employer share is not on the payslip. The Government Contributions table on the payroll run page shows the run's totals for both shares and EC.
Timekeep does not do the year-end tax adjustment or BIR Form 2316. Your accountant does those.
Common problems
- An amount is still wrong after I fixed a setting. Payslips already made keep their amounts. If the run shows Draft, follow Rerun a draft payroll. Rerun the 1st cutoff first, then the 2nd, because the 2nd reads what the 1st took.
- The 2nd cutoff took less SSS than the 1st. This is expected. The 2nd cutoff works out the month on actual pay, then takes what is left after the 1st. If Ana earns ₱11,000 in the 2nd cutoff, her month is ₱24,000 and her SSS ₱1,200, so the 2nd cutoff takes ₱550.
- A weekly employee had no SSS, PhilHealth or Pag-IBIG taken. Their schedule is set to 1st Cutoff Only or Last Cutoff Only, and weekly payroll never deducts on those. Set Government Contribution Schedule to Every Cutoff (50/50) on the employee, or choose Both cutoffs (half each) for everyone, then rerun the draft.
- No withholding tax was taken. Pay after contributions was ₱10,417 or less for the cutoff, or ₱4,808 for the week. Or Withholding Tax is off on the employee's Deductions card.